Strong Demand for High-Spec Offices in Athens Continues into 2026
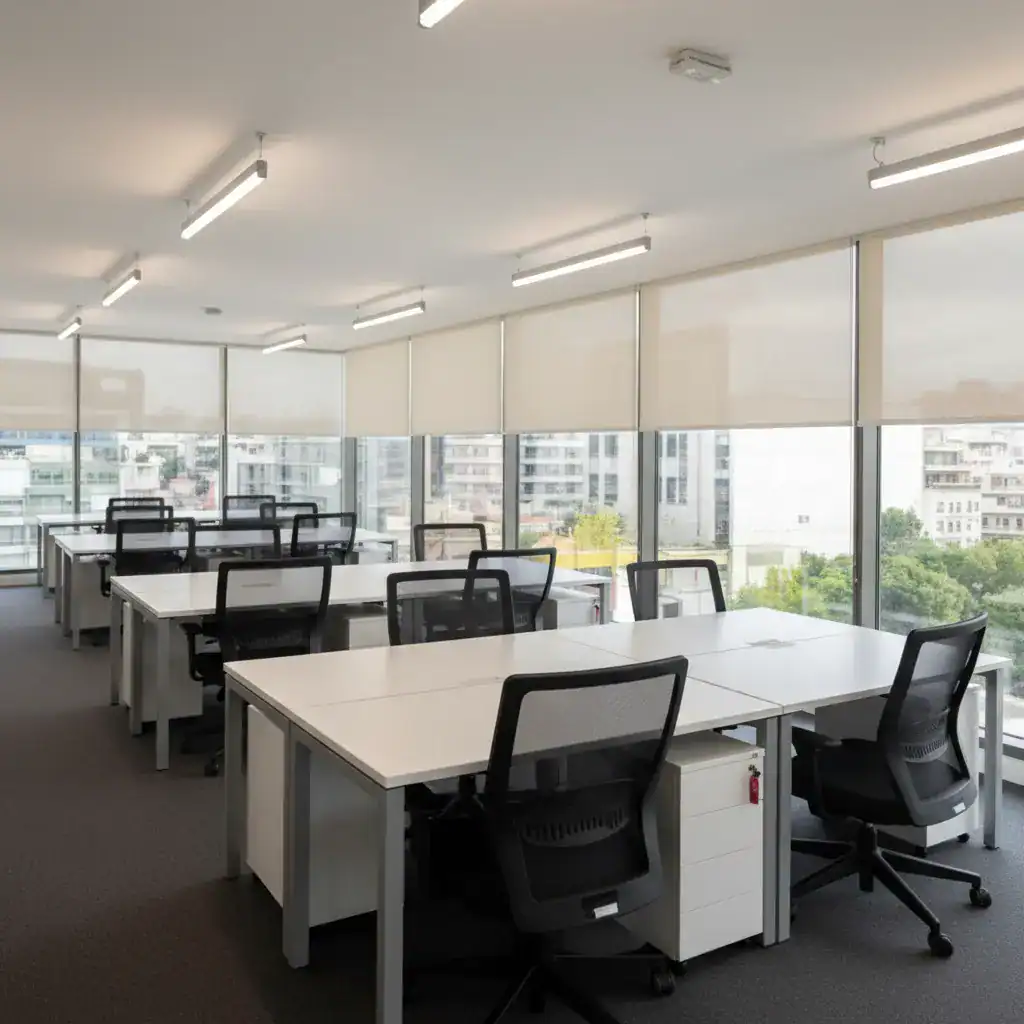
Athens, March 26, 2026 – The demand for high-specification and energy-efficient office spaces in Athens is expected to remain strong throughout 2026, despite broader economic challenges. Companies are increasingly seeking ‘green’ and bioclimatic offices in prominent locations, a trend that is set to boost new leasing activity. Currently, projects under development total 350,000 square meters.
These insights are drawn from the latest analysis of the Athens real estate market for the second half of 2025, conducted by DANOS, a consulting firm in collaboration with BNP Paribas Real Estate.
Market Overview and Supply
According to DANOS’ data, the total office stock in Athens stands at 2,980,000 square meters. New office supply accounts for 108,000 square meters, with new developments or renovations contributing an additional 241,000 square meters, bringing the total new and renovated space to 350,000 square meters. The average office vacancy rate in the capital is currently 8.5%.
Rental Prices on the Rise
In terms of rental prices, prime locations in central Athens have seen average prices climb to 31 euros per square meter. Kifissias Avenue follows closely at 29 euros per square meter, while Vasilissis Sofias Avenue commands 28 euros per square meter.
Market Trends and Driving Factors
The Greek office market experienced a mixed performance last year, with slower leasing activity earlier in the year followed by a partial recovery. This occurred within a context of limited new supply and robust demand for quality, energy-efficient spaces.
The strongest demand came from companies in the technology, financial, and consulting sectors. Additionally, flexible workspaces (co-working) have gained traction, and renovations of historic buildings in central Athens have increased. Sustainability and proximity to transportation infrastructure are now key factors driving value in this real estate category, with deals nearing 200 million euros by the end of the second half of 2025.
“Major players such as Real Estate Investment Companies, Prodea, Grivalia, and international funds fueled transactions. Domestic institutional investors acquired a portfolio of Class A offices worth 70 million euros in the second half of 2025. Dimand also finalized a deal for offices in Marousi with a private seller,” the analysis states. It further adds that the new significant developments include the ION Group’s project, which plans a total investment of 2 billion euros in the Ellinikon project, encompassing office spaces.
Overall, the market sentiment is neutral to positive. While the office sector lags behind the tourism industry-which currently attracts the most investment interest due to its growth-it shows a steady recovery and development. This is primarily driven by demand in conditions of limited supply of quality spaces. Rents and prices for high-specification offices saw slight increases, particularly in the city center and northern suburbs. Based on the limited available data for 2025, prices for high-specification offices in the greater Athens area increased by 0.9% (H1 2025 vs. H2 2024), while in the rest of Greece, the corresponding growth rates were +0.3%.
By the end of 2025, rents in prime locations for quality spaces ranged from 29-31 euros/sqm/month in the Central Business District (CBD) and approximately 29 euros/sqm in the northeastern axes. Athens remained competitive in terms of cost compared to other European cities. Office vacancy rates in the capital were approximately 9.8%-10% by the end of 2025, compared to 9.5% at the end of 2024, following positive demand.
The demand for modern, high-quality, Class A offices with green certifications exceeded supply, particularly in high-value central areas such as Syntagma, Kolonaki, and Marousi, pushing rental prices to 30-35 euros/sqm/month. Concurrently, the limited supply of new constructions and increased interest in renovated buildings along key avenues (e.g., Kifissias, Mesogeion) maintained upward trends, with rents in these areas ranging from 20-25 euros/sqm/month.
In 2025, vacancy rates remained relatively low, continuing the trend from 2024. By mid-2025, the total stock, as mentioned earlier, reached 2.98 million square meters, boosted by new supply, while leasing activity in the third quarter amounted to 50,000 square meters, despite a slight year-on-year decrease.
As highlighted in the DANOS analysis, investors prioritized sustainability, green certifications, and well-connected locations, ultimately boosting values in central Athens. Notably, the city center’s share of total demand reached 44%.
Source: DANOS, BNP Paribas Real Estate, Newmoney.gr